Best Money Apps 2026: 9 Picks to Stretch Every Dollar
Deal hunting is only half the game. You can score the lowest price on earth and still leak cash if the money never lands in the right place afterward. That is where the best money apps earn their keep in 2026 by rounding up spare change, flagging price drops, and automating the boring parts of saving so your bargains actually add up. This guide ranks the tools that pair perfectly with a frugal, coupon-clipping lifestyle.
I have tested dozens of these over the past three years, from cashback trackers to peer-to-peer wallets. Below are the ones that survived real-world use: the apps I still open weekly, not the ones that got deleted after the sign-up bonus cleared.
Why the best money apps matter for bargain hunters
Every deal you chase has a hidden second step: moving, storing, and growing the money you saved. A $40 discount means nothing if it evaporates into impulse buys. Good apps close that loop automatically.
According to the Consumer Financial Protection Bureau, Americans who automate savings transfers build emergency funds roughly twice as fast as those who save manually. Automation beats willpower, and that is exactly what these apps sell.
- Cashback and rebates — recover a slice of every purchase.
- Round-ups — micro-invest the change from each swipe.
- Price tracking — alert you before you overpay.
- Peer payments — split group buys without the awkward math.
The 9 best money apps to try this year
I grouped these by job. Most frugal shoppers run three or four at once: one cashback tool, one payment wallet, and one automated saver. Mix and match to fit your spending.
Cashback and rebate apps
Rakuten and Fetch remain the heavyweights. Rakuten pays straight cashback at thousands of retailers, while Fetch turns any receipt into points. Stack them with store coupons and you often double-dip on a single haul.
Payment and transfer wallets
For splitting a bulk grocery run or paying back a friend, a fast peer wallet is essential. If you are new to mobile payments, this Cash App guide walks through setup, fees, and the safety habits that keep your balance protected.
Automated savers and investors
Acorns rounds up purchases into a diversified portfolio, and Chime auto-saves a percentage of every deposit. Both run silently in the background, which is the whole point.
Quick comparison of the top contenders
| App | Primary job | Typical fee | Best for |
|---|---|---|---|
| Rakuten | Cashback | Free | Online shoppers |
| Fetch | Receipt rewards | Free | In-store buyers |
| Acorns | Round-up investing | $3/mo | Hands-off savers |
| Chime | Auto-save banking | Free | Fee-averse users |
| Cash App | Peer payments | Low/free | Splitting costs |
How do I pick the right money app for my habits?
Start with your biggest leak. If you overspend online, lead with cashback. If group buys drain you, prioritize a payment wallet. If saving never happens, automate it first. You do not need all nine; you need the two or three that match where your money actually goes.
- Track one month of spending to find your largest category.
- Pick the single app that attacks that category hardest.
- Turn on automatic transfers so saving is not a daily decision.
- Review results after 30 days and cut anything you ignored.
- Add a second app only once the first becomes a habit.
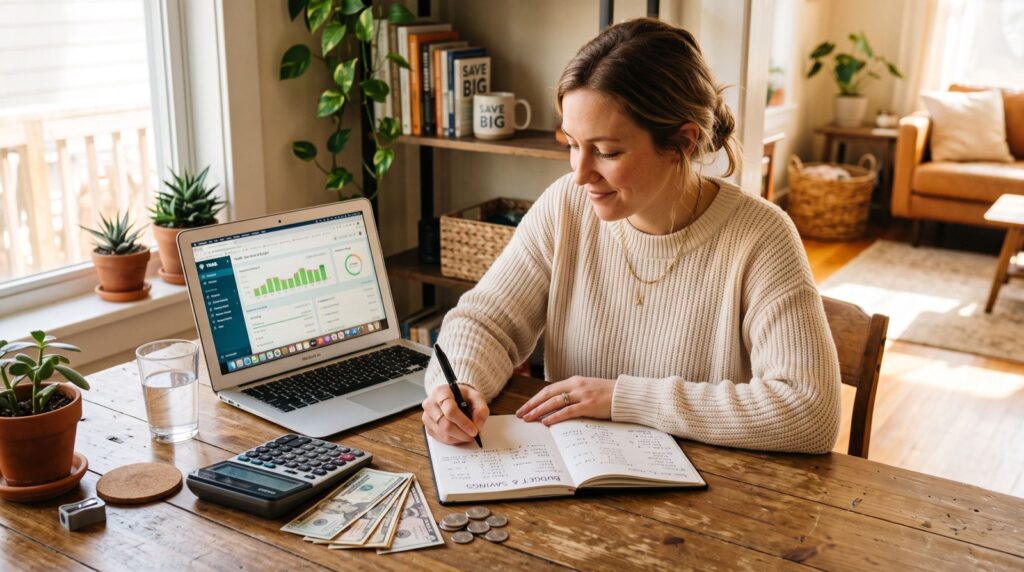
One original tip from my own testing: schedule round-ups and cashback payouts to land on the same day each month, then sweep that total into a high-yield account. Treating scattered micro-savings as a single monthly “paycheck to yourself” makes the progress visible and keeps you motivated.
Smart money habits that multiply your savings
Apps are tools, not magic. Pair them with a few disciplines and the compounding gets real. The FDIC Consumer News recommends keeping an emergency buffer in an insured account before chasing yield, which is advice worth following even in a bull market.
Bulk buying is a classic frugal move, but it only pays if you can store the surplus safely. If you shop wholesale and run out of space at home, an experienced local team can help you stash overflow without renting a pricey unit you barely use.
Finally, audit your subscriptions quarterly. The average household in 2026 pays for several services it forgot about, and a quick sweep often frees up more cash than a month of coupon clipping.
Mistakes that quietly cancel your savings
Even disciplined shoppers sabotage themselves with small, invisible errors. The most common is chasing a deal on something you never needed, which turns a 50 percent discount into 100 percent waste. A coupon is not a reason to buy; it is a reason to buy cheaper something you were already going to purchase.
The second trap is ignoring fees. Instant-transfer charges, ATM surcharges, and foreign-transaction fees nibble away at your hard-won savings. Before you commit to a wallet, read the fee schedule and route non-urgent transfers through the free standard option. The best money apps make those fees transparent, so you always know the real cost of moving a dollar.
A third mistake is letting cashback sit idle in an app balance earning nothing. Sweep it into an interest-bearing account on a set schedule so your rewards keep working. Treat every dollar as an employee: if it is not earning interest or buying something you value, it is slacking off.
Finally, do not confuse activity with progress. Downloading ten apps feels productive, but if you never check them, you have simply added clutter. Measure outcomes in actual dollars saved each month, not in the number of tools on your phone.
Building a simple weekly money routine
Consistency beats intensity. A short, repeatable routine keeps your deal hunting and saving aligned without eating your weekends. Here is a lightweight rhythm that takes under 20 minutes a week.
- Monday: scan price-drop alerts for anything on your wishlist.
- Wednesday: upload receipts to your cashback and rewards apps.
- Friday: sweep round-ups and cashback into savings.
- Sunday: review the week’s spending and plan next week’s buys.
Lock this routine to times you already have free, like a coffee break, and it will stick far longer than a rigid daily plan. Small, boring consistency is what separates people who talk about saving from people who actually have savings.
Frequently Asked Questions
Are the best money apps safe to use?
Reputable apps use bank-grade encryption and keep funds in FDIC-insured partner banks. Enable two-factor authentication, never share your login, and only download from official stores to stay protected.
How many money apps should I run at once?
Two to four is the sweet spot: one cashback tool, one payment wallet, and one automated saver. More than that and you tend to ignore the extras, which cancels the benefit.
Do cashback apps really pay out?
Yes, though payouts can take a few weeks to clear after a purchase posts. Keep expectations realistic: cashback typically returns 1 to 10 percent, so treat it as a bonus on deals you were already making.
Which app is best for splitting group purchases?
A peer-to-peer wallet like Cash App or Venmo handles splits instantly. For recurring group buys, pick one everyone already uses so nobody stalls on downloading something new.
Final take
The best money apps of 2026 are the ones that quietly automate the habits you would otherwise skip. Pick two or three that match your real spending, let them run in the background, and watch small, boring transfers snowball into a genuine cushion. Start with one today, measure the results next month, and keep only what earns its place on your home screen.